Awendio Solaris
at RE+ 2026
Preparation, findings and next steps
What we built for the show, what the strategy workshop found, and what we decide today.
Las Vegas Convention Center · 17 to 19 November 202615 November 2026
Seven workstreams prepared for the show
1
Exhibitors scanned and categorised
1,311 scanned, 790 kept, AI plus manual review
2
Every deal ranked 1 to 4
As a client and as a partner, by type
3
Priority companies researched
401 verified contacts, 317 emails, 13 meetings
4
Sorted, summarised, assigned
Priority order, company summaries, two owners
5
Lead communications
Notes, angles, stand outcomes, business cards
6
Walk map by person and day
201 stops on the real floor plan
7
Workshop on our approach
Draft strategy to finalise today
→
Then
Findings (12 slides) and today’s action points
All figures from the Awendio Solaris console, 15 Nov 20262
Every exhibitor scanned and categorised
1,311
exhibitors in the RE+ directory scanned
790
kept as relevant exhibitors
982
deals, with Awendio’s own target list
How it was done
AI read every exhibitor’s profile and suggested a relation (client, partner or competitor), a type and a rank, each with its reason. Vivian then reviewed and corrected the categories by hand.
Result: 268 client deals, 628 partner deals and 86 competitors, each filterable by type, rank, engagement and market.
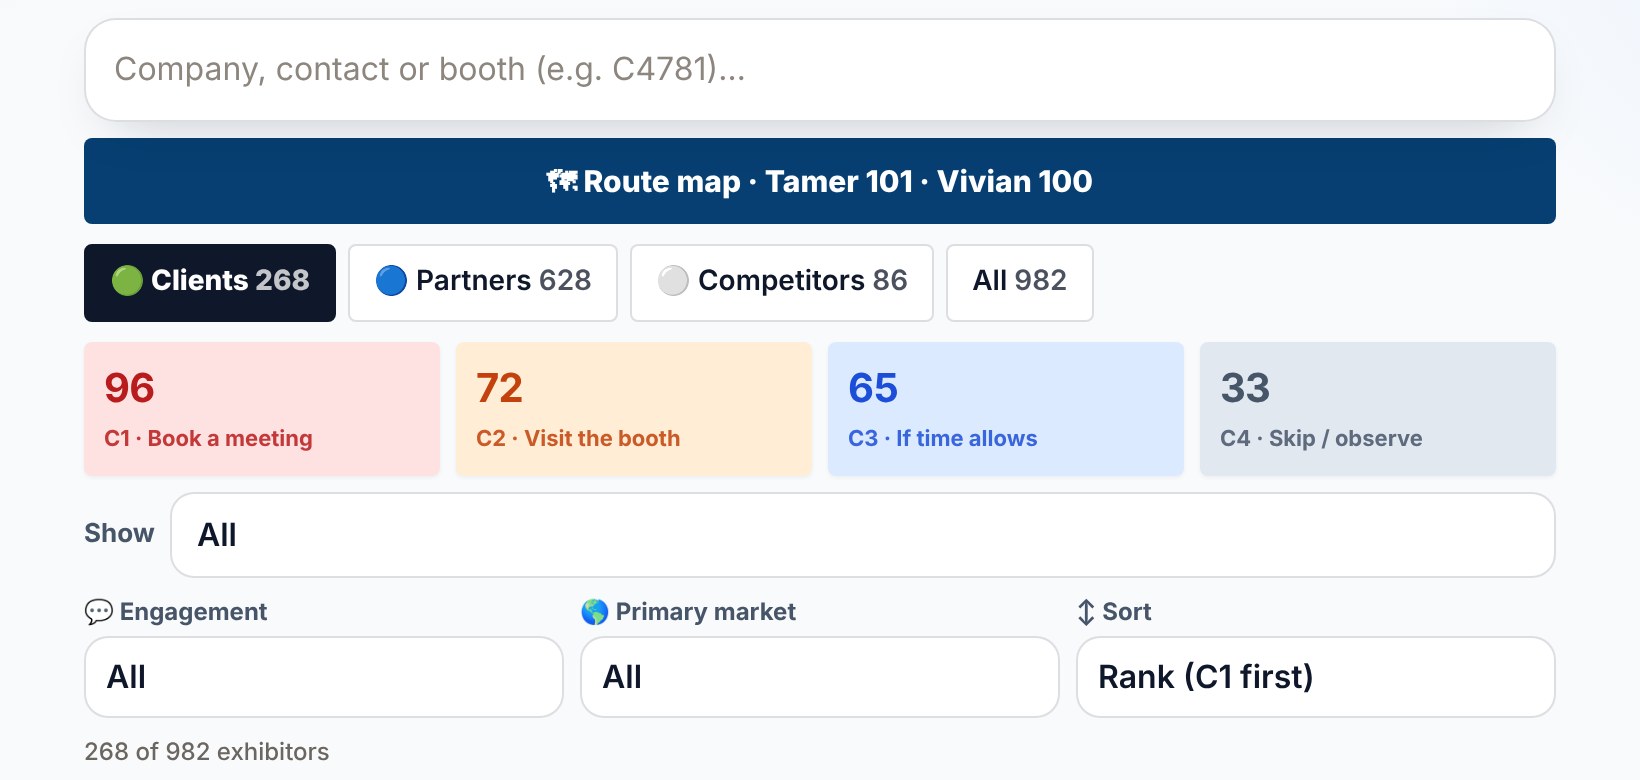
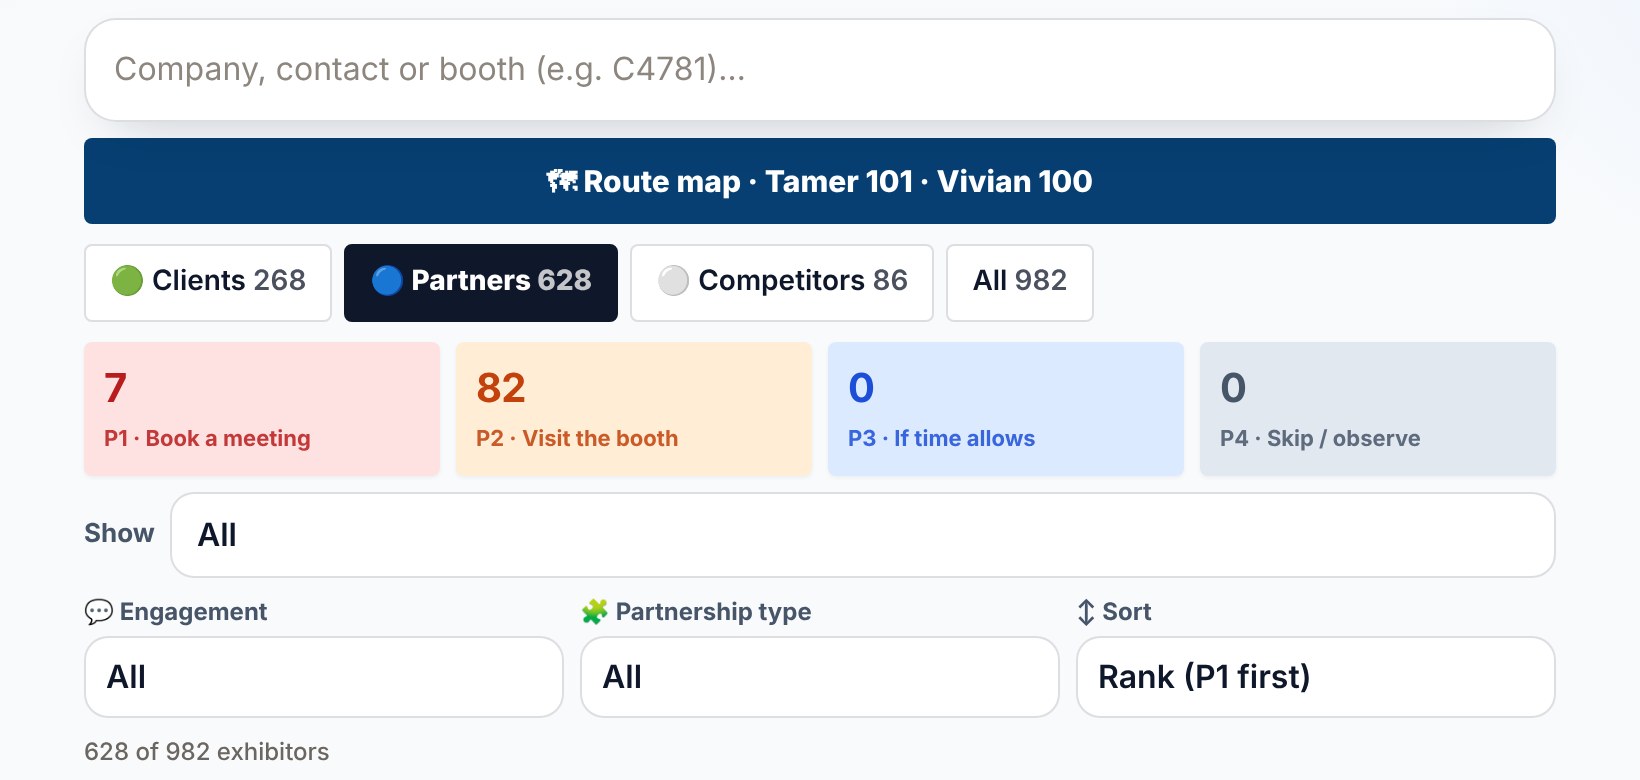
Screens: the RE+ 2026 panel, client and partner views3
Every deal ranked 1 to 4, as client and as partner
| Client type | C1 | C2 | C3 | C4 | Total |
|---|---|---|---|---|---|
| Developer / IPP | 50 | 21 | 21 | 2 | 94 |
| EPC | 28 | 25 | 22 | 2 | 77 |
| Asset owner, utility | 8 | 7 | 6 | 1 | 22 |
| Distributor | 2 | 7 | 3 | 0 | 12 |
| Installer | 2 | 2 | 6 | 3 | 13 |
| Installation subcontractor | 0 | 0 | 2 | 12 | 14 |
| Electrical subcontractor | 0 | 0 | 3 | 9 | 12 |
| Other | 6 | 10 | 2 | 4 | 22 |
| Total | 96 | 72 | 65 | 33 | 266 |
| Partner type | P1 | P2 | Total |
|---|---|---|---|
| Technical advisory | 1 | 46 | 47 |
| Bundled energy products | 0 | 18 | 18 |
| Owner’s engineering, CM | 2 | 8 | 10 |
| Financing | 1 | 7 | 8 |
| Warranty insurers | 2 | 2 | 4 |
| Market intelligence | 1 | 1 | 2 |
| Total | 7 | 82 | 89 |
Outside Awendio’s brief, set to rank 5 with no contact: 539 partners and 2 clients. Competitors tracked separately: 86.
Source: Awendio Solaris console, 15 Nov 20264
Priority companies researched and contacted
982
company profiles: who they are, why they may buy
401
deals with a verified decision-maker contact
317
pre-show emails sent; 240 opened
13
meetings confirmed; 5 more replies open to meet
How it was done
Each priority client and partner was researched for company facts and decision makers. Contacts were verified on the company’s own domain. Personalised emails from Tamer’s Awendio mailbox asked to meet at the show.
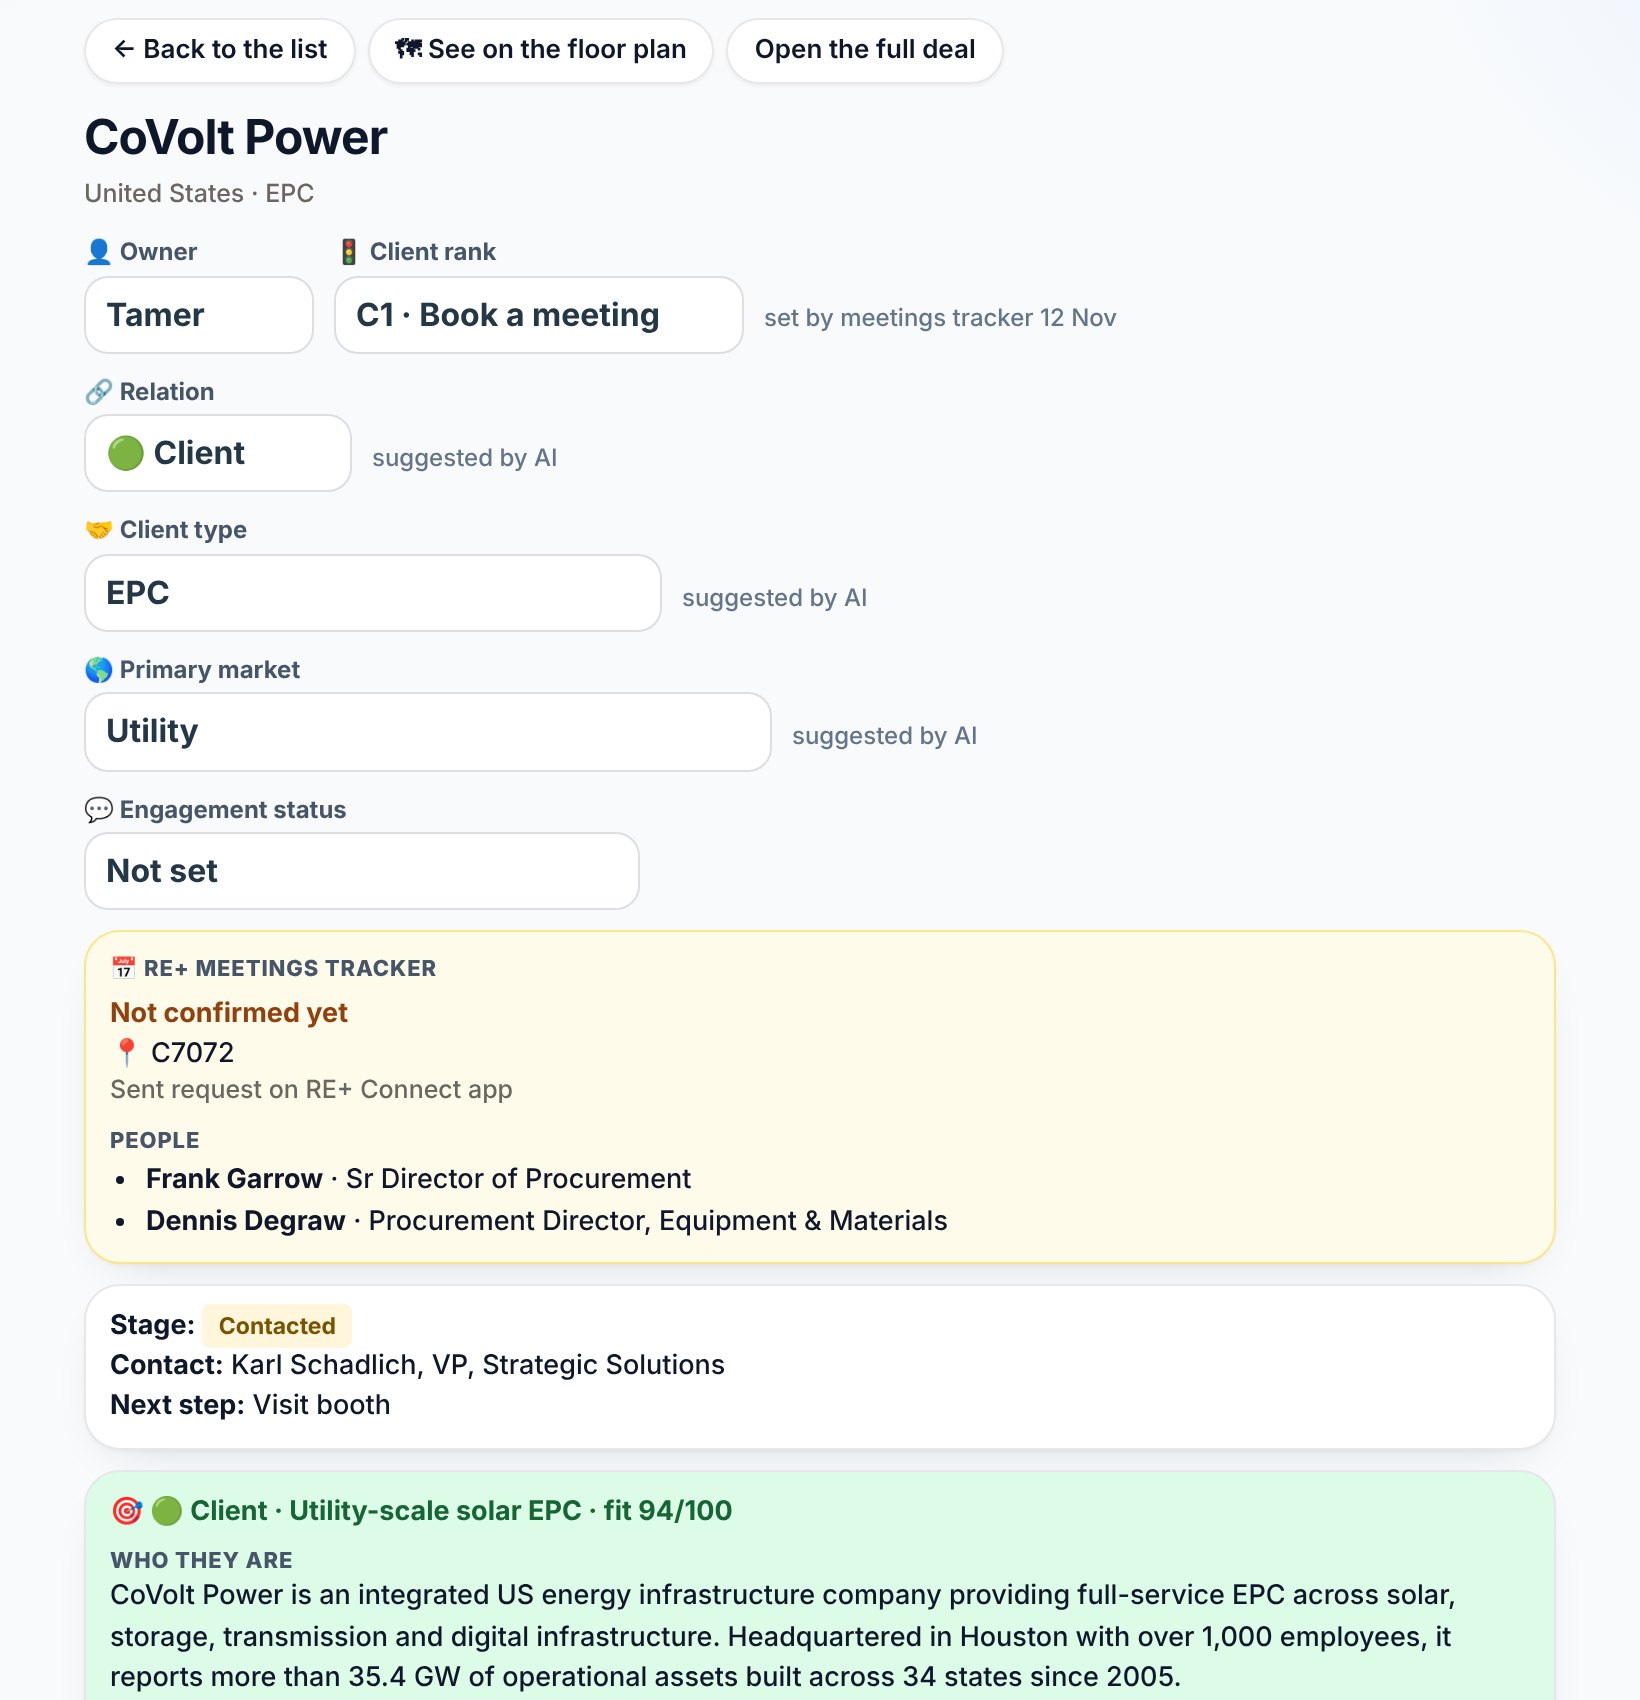
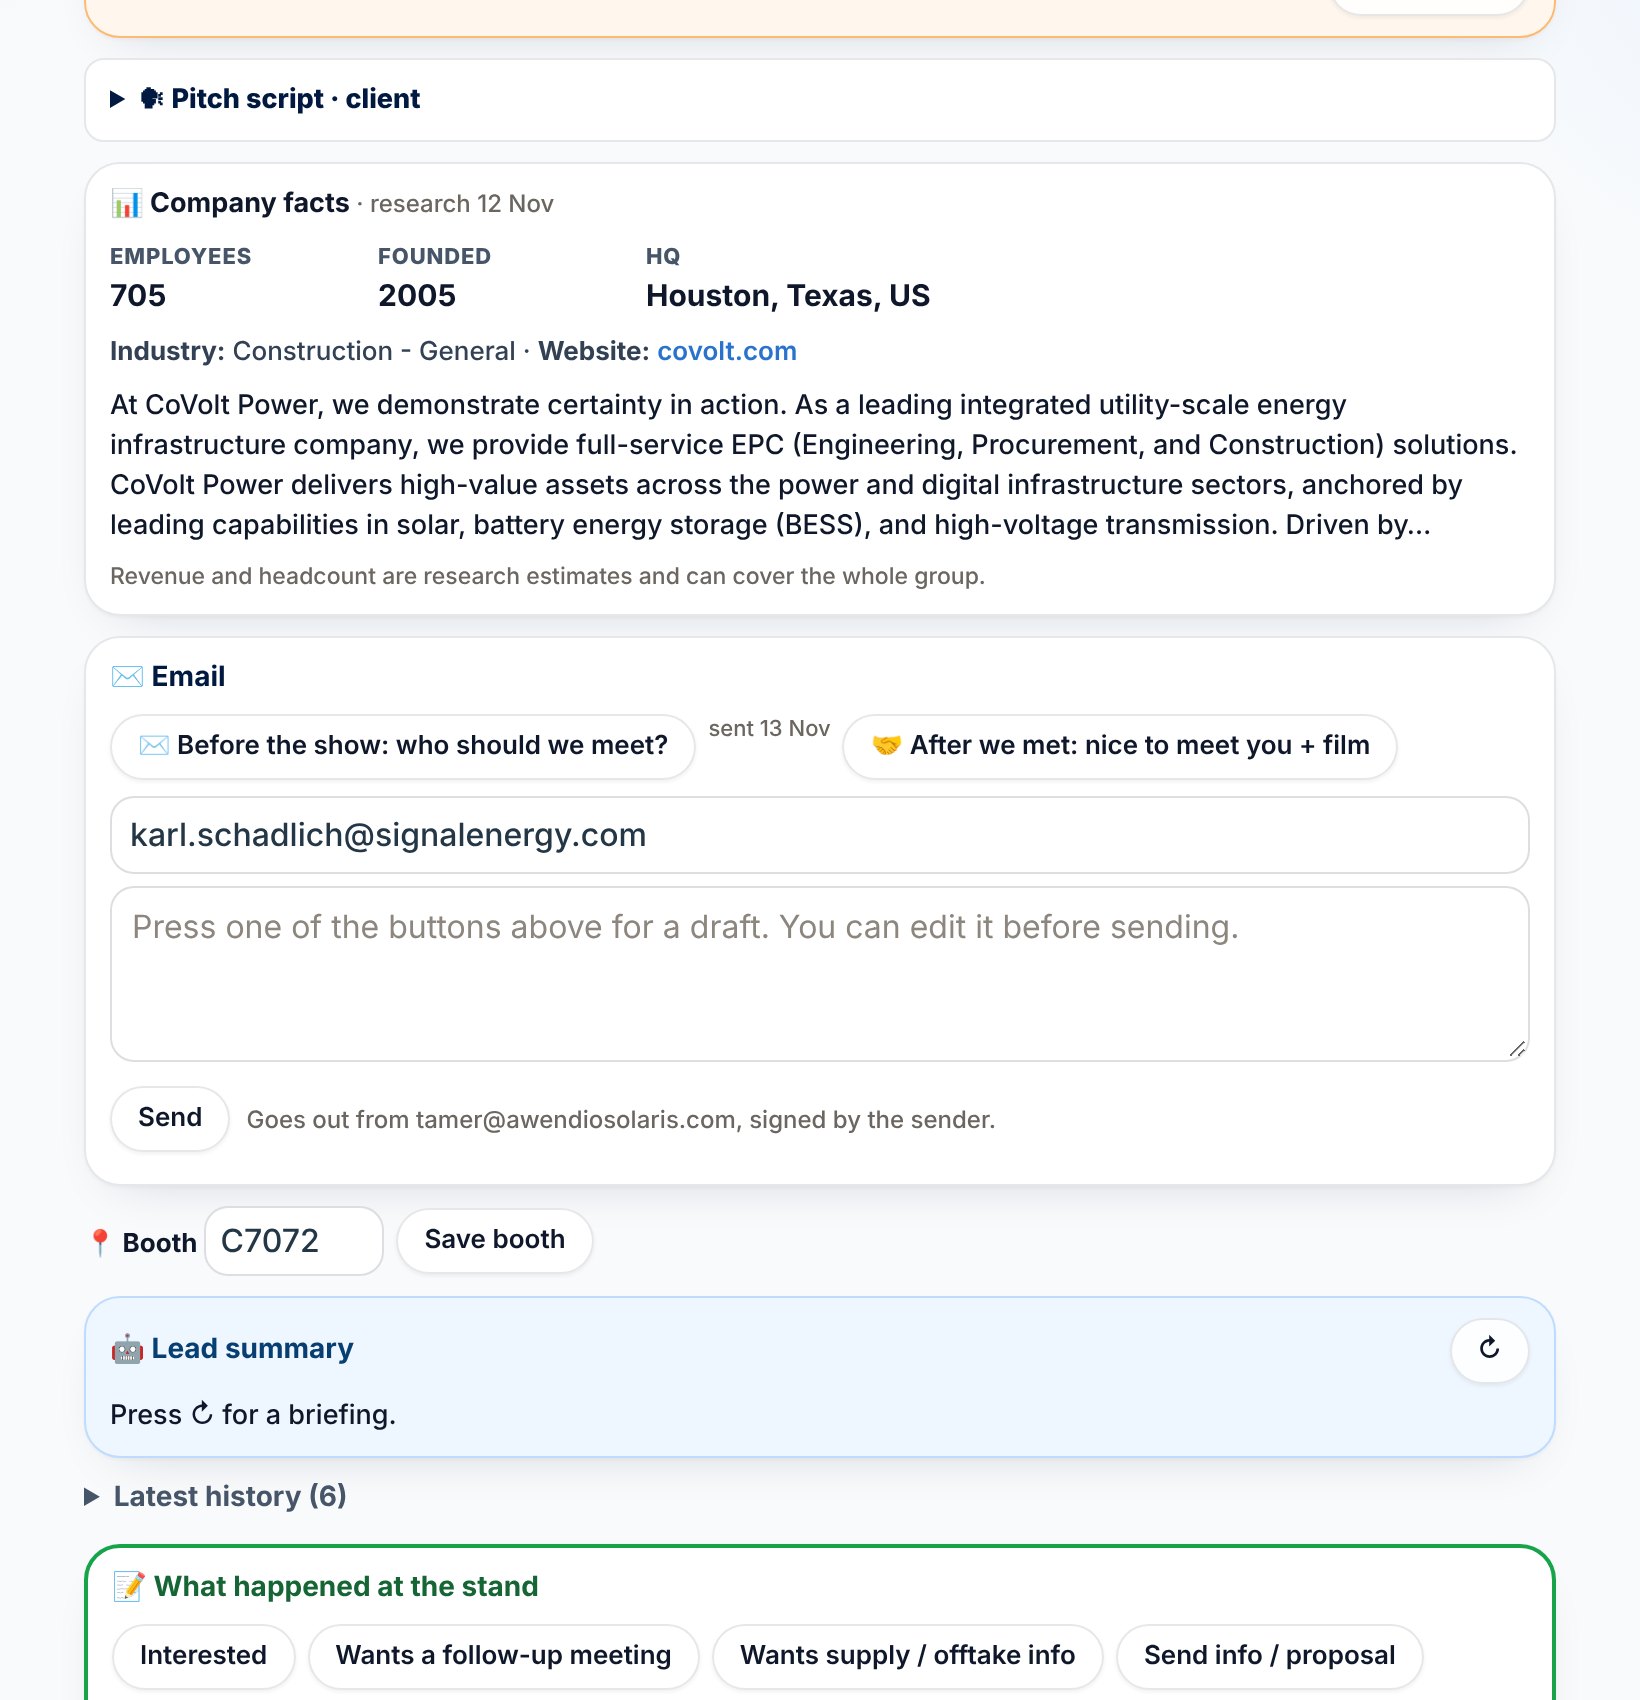
Screens: a C1 deal, its company profile and the email sent on 13 Nov5
Every deal sorted, summarised and assigned
Priority order
Deals open in rank order, C1 first, then by fit. Each card shows booth and walk number, rank, relation, stage, owner, the contact and a two-line company summary.
101
show targets for Tamer, the warmest: 42 email contacts and the C1 / P1 booths
100
show targets for Vivian: P/C 2 to 4 booths on one stretch of the floor
One search finds any company, contact or booth number, on the phone at the show.
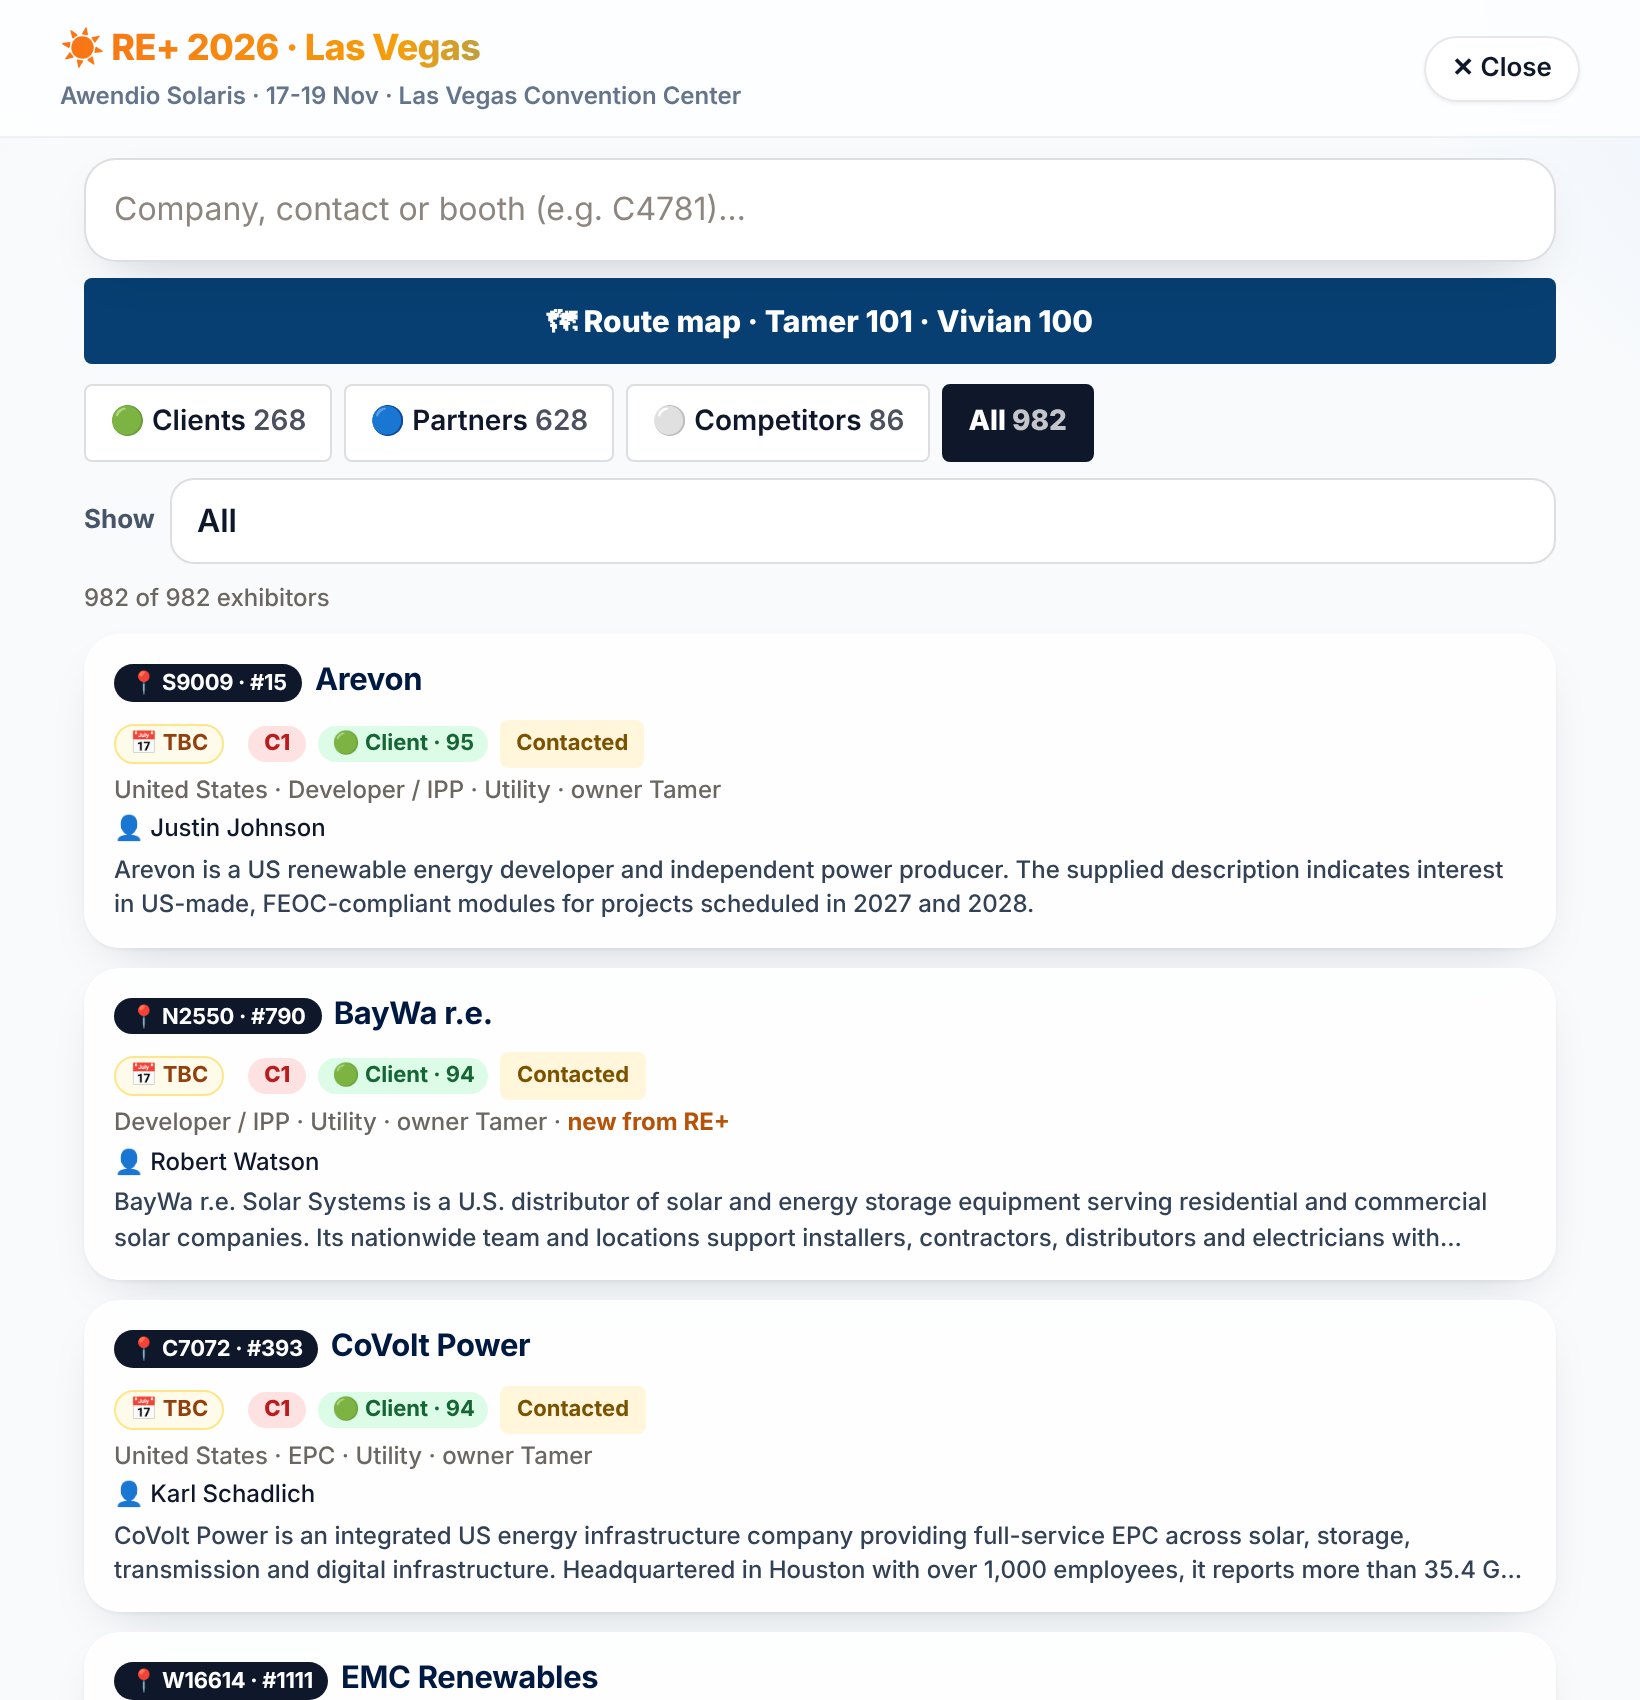
Screen: the deal list in priority order6
All lead communication in one place
Angle of approach
Dated, signed notes per deal on how to open and what to lead with.
What happened at the stand
Outcome in one tap, meeting notes, the person met and a follow-up date.
Business cards and history
A photo of a card fills the contact’s details; every email, reply and note stays on the deal.
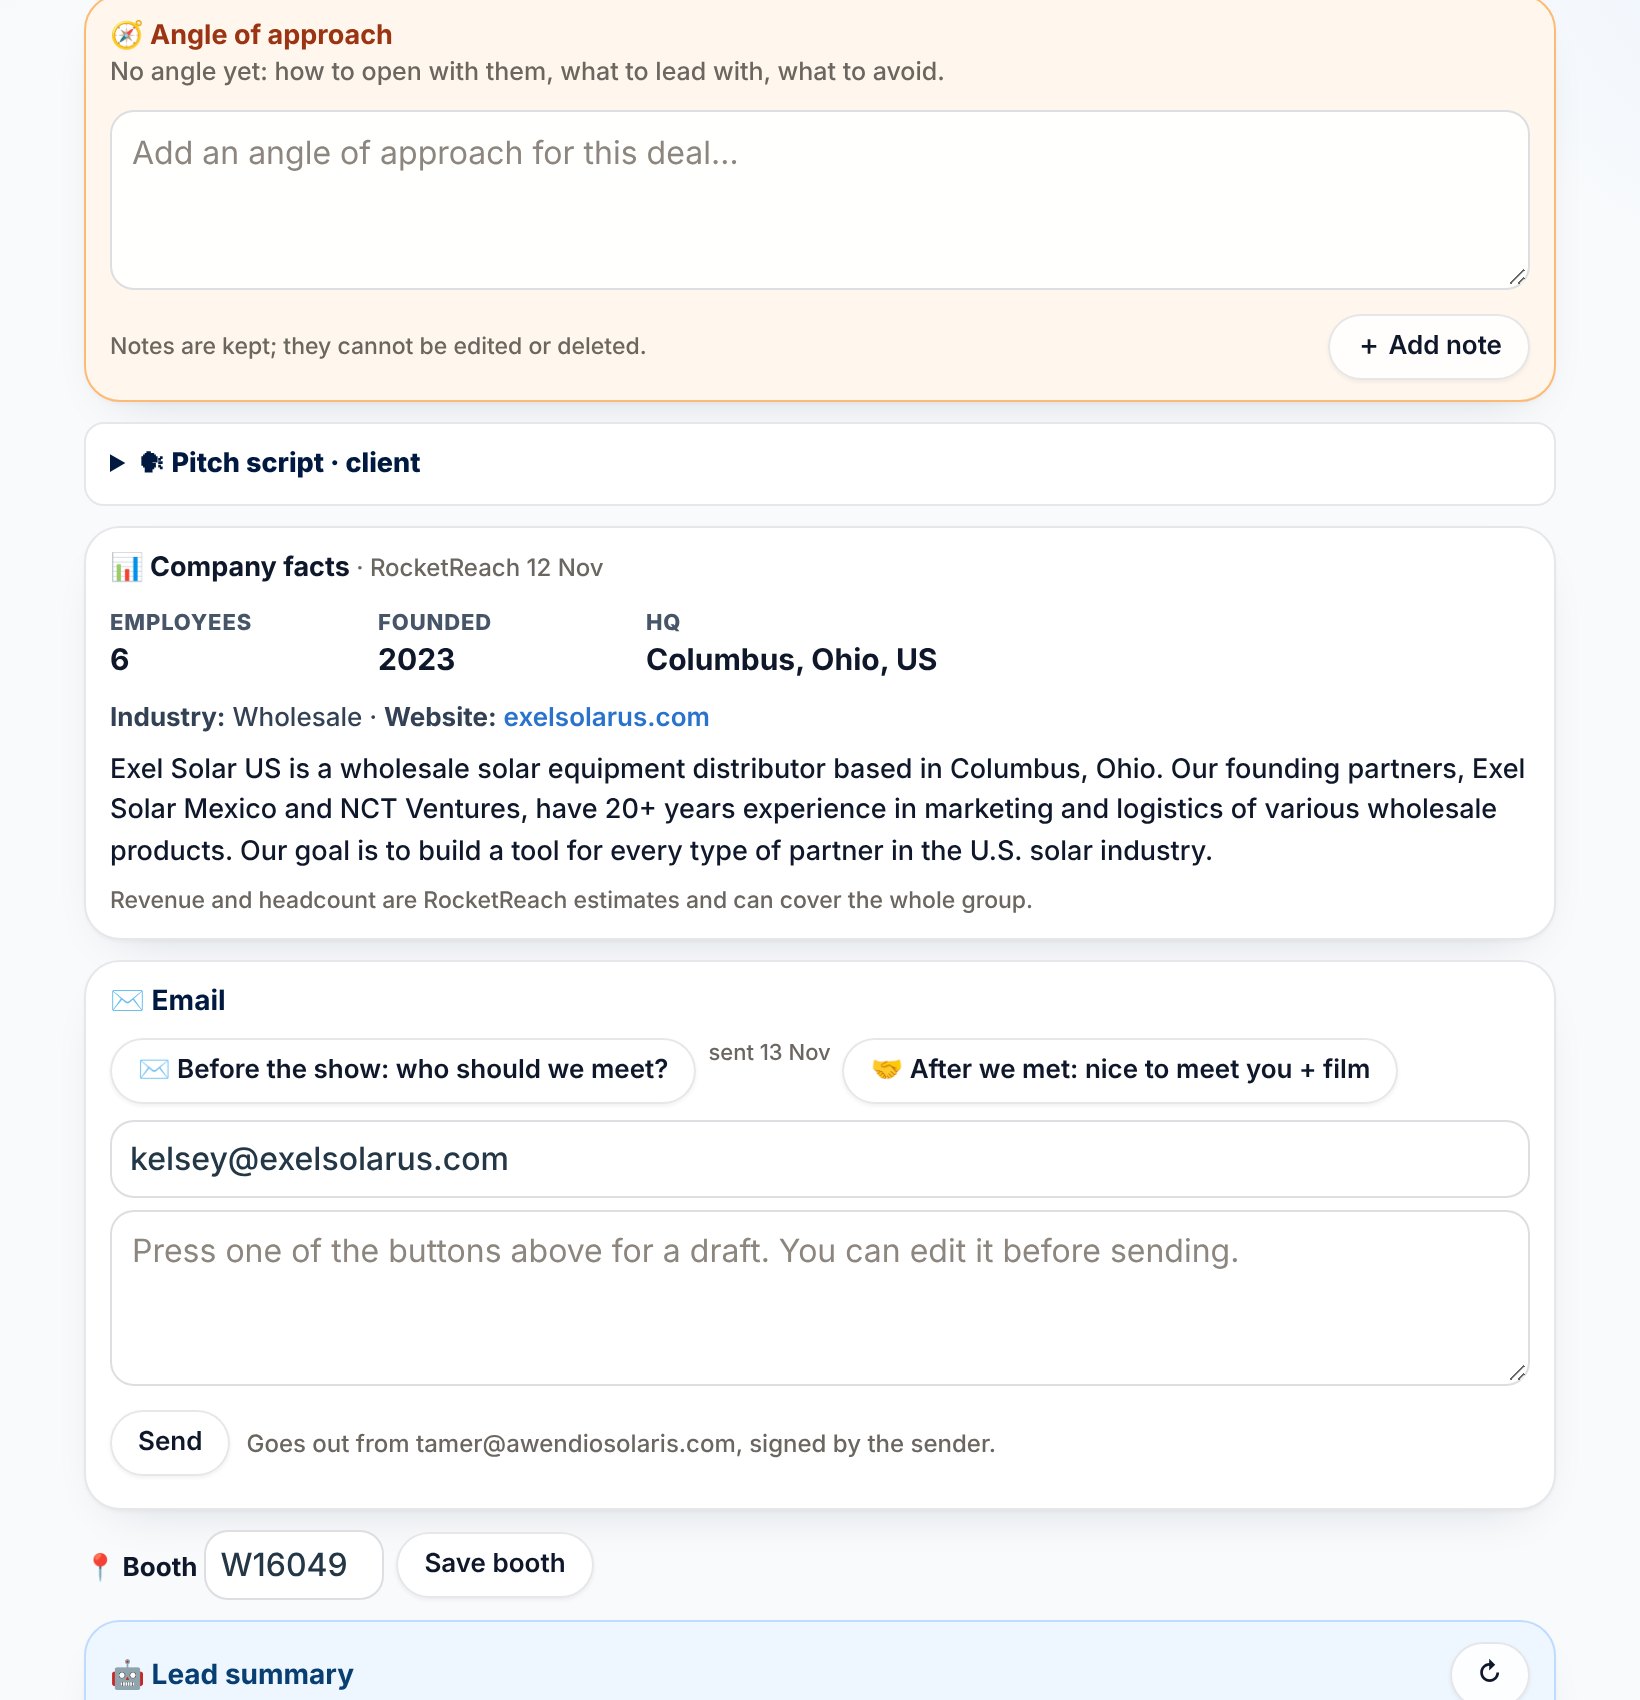
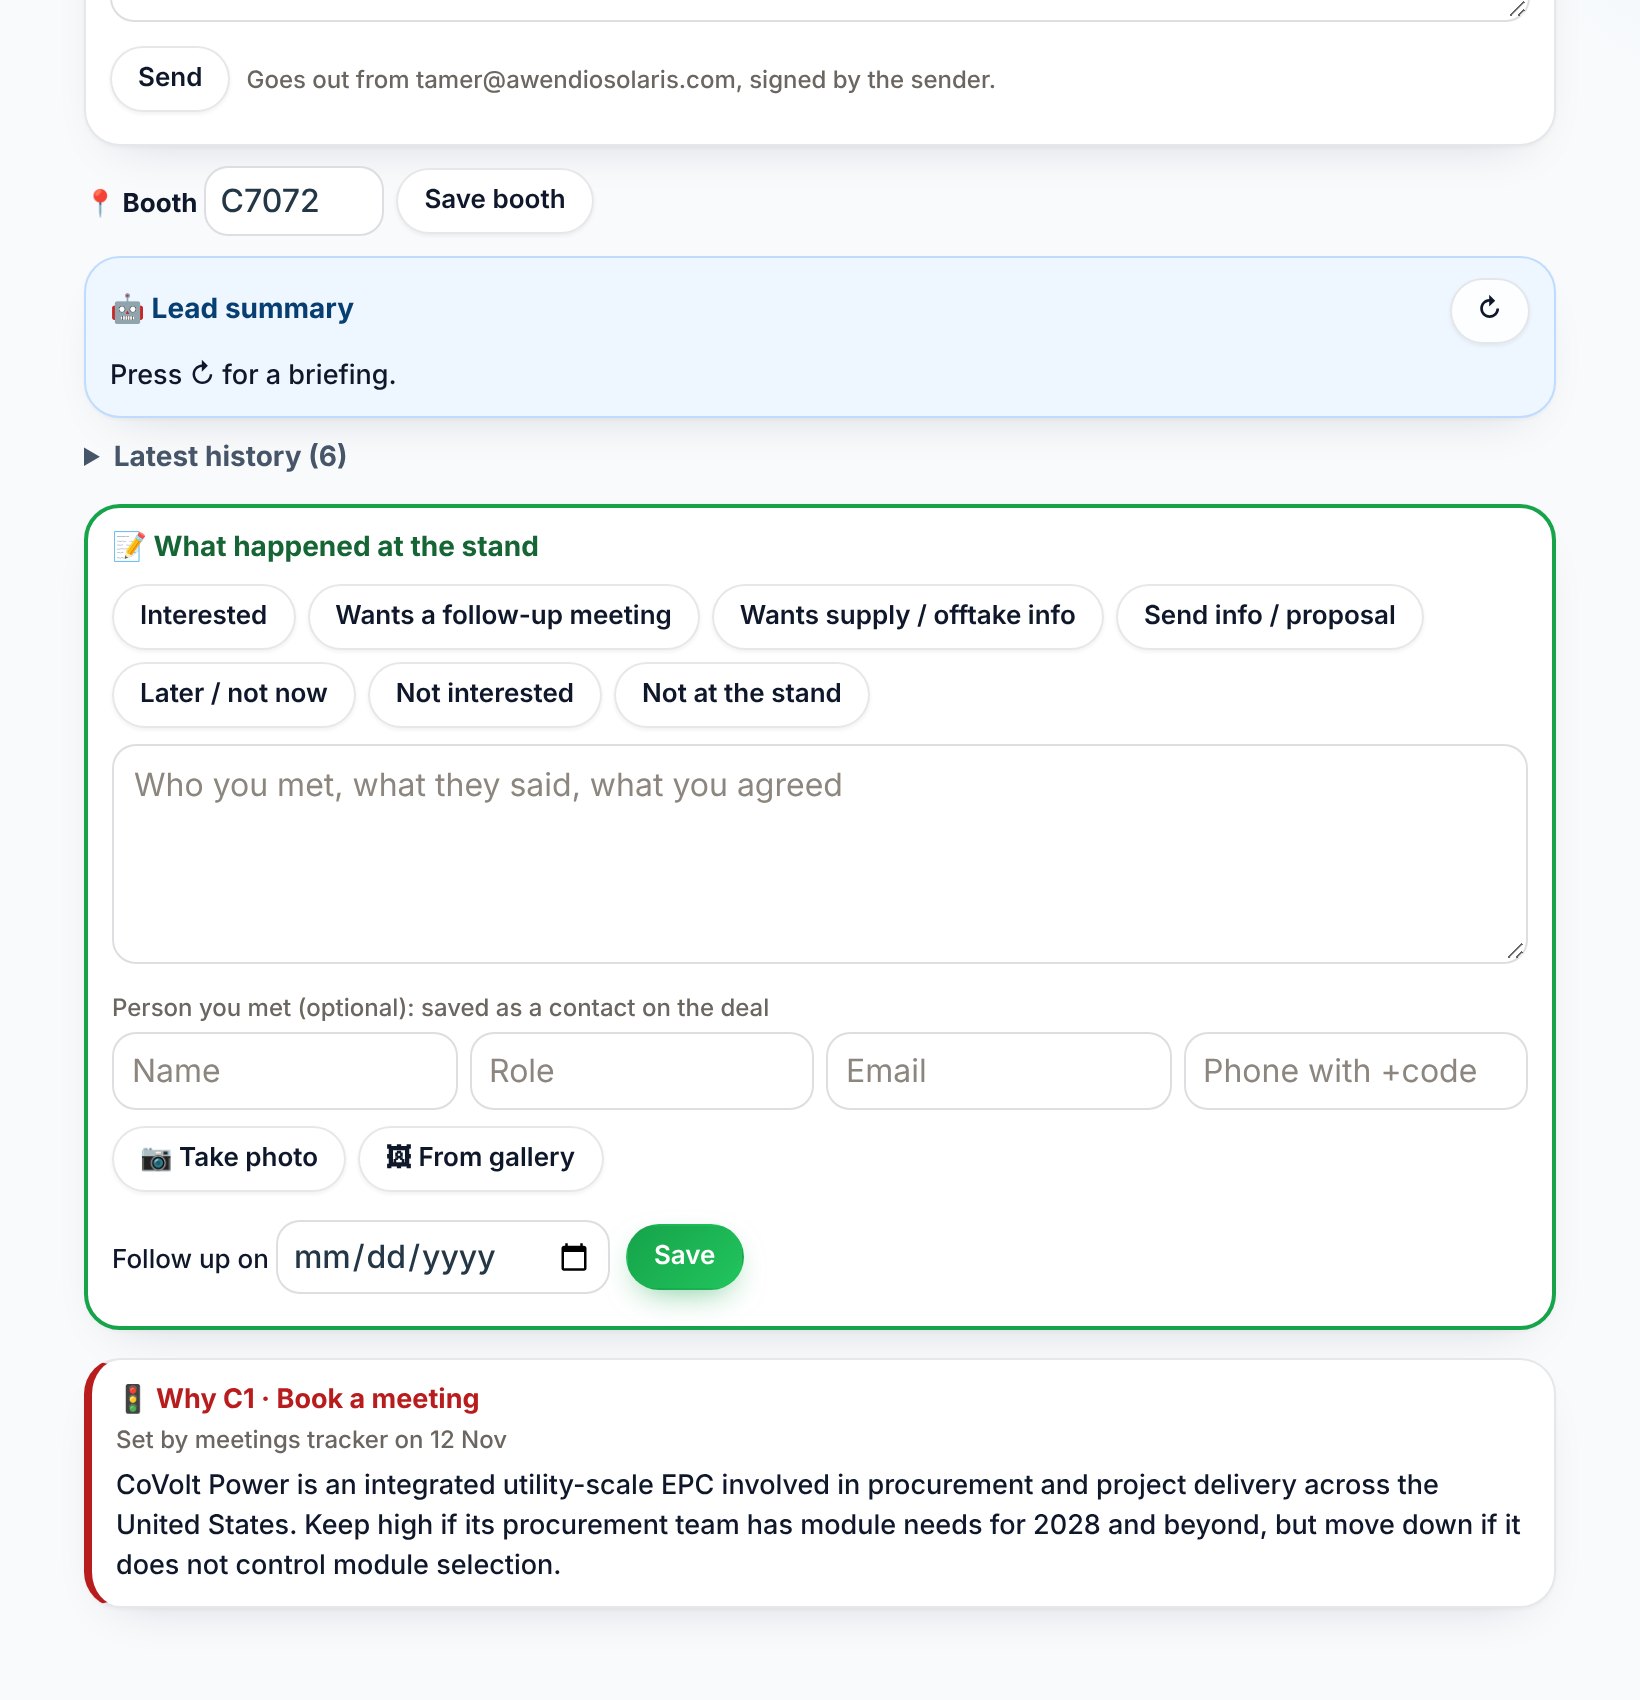
Screens: angle of approach notes and the stand log with business-card capture7
A walk map for every person and every day
201
stops on the real floor plan
101 · 100
Tamer · Vivian
4
halls, 17 to 19 Nov
How it works
Every priority company is placed at its booth. The route runs from the nearest entrance, meetings stay on their date and time, and colours show emails exchanged and rank. A tick or a move to another day shows on both phones at once.
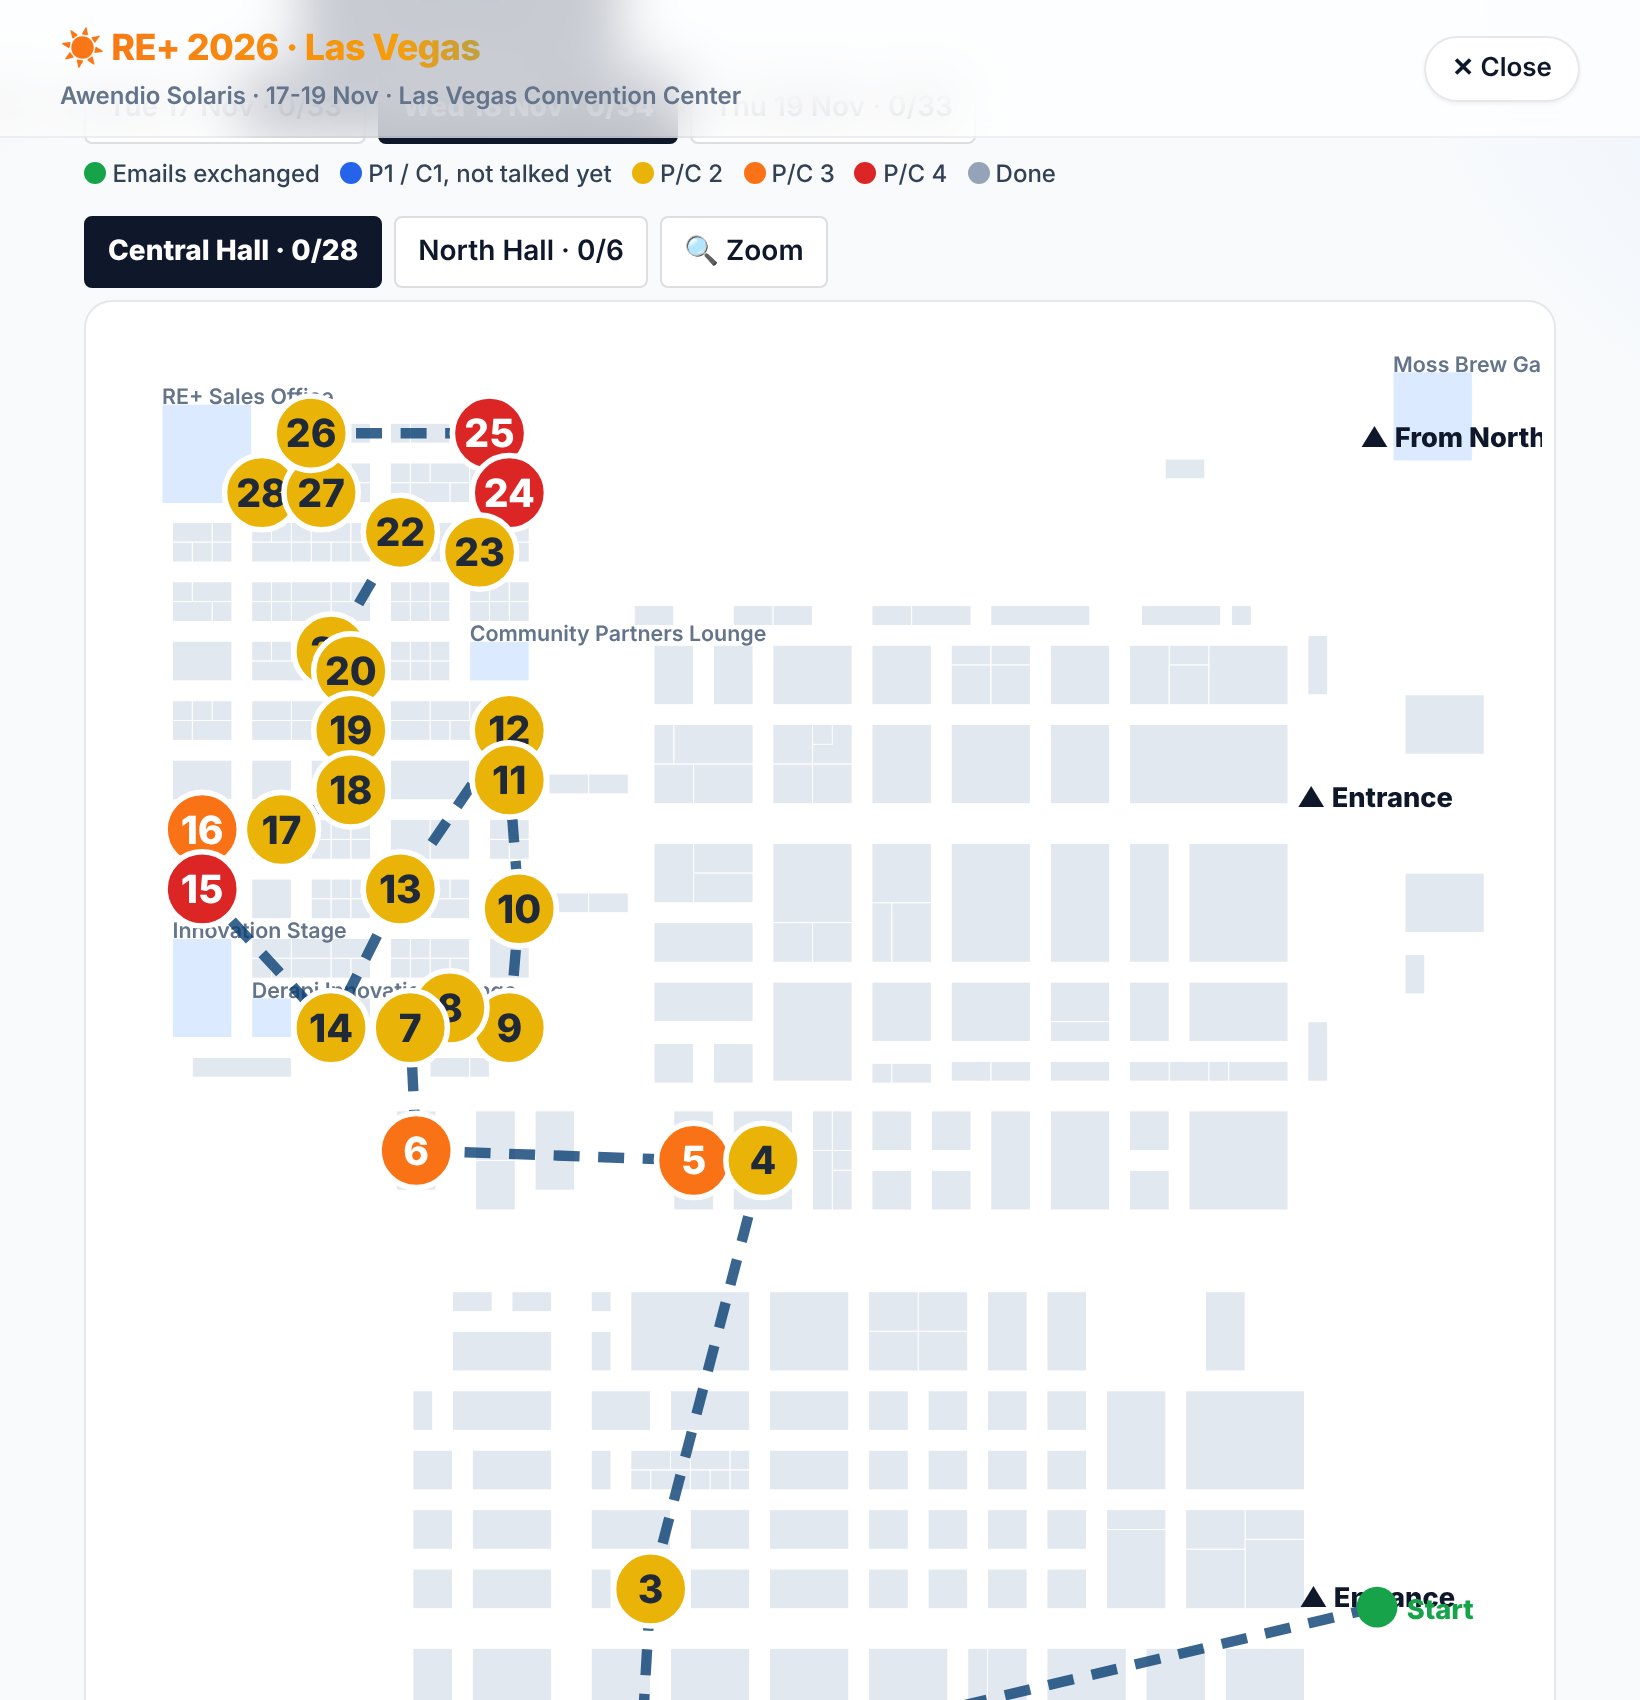
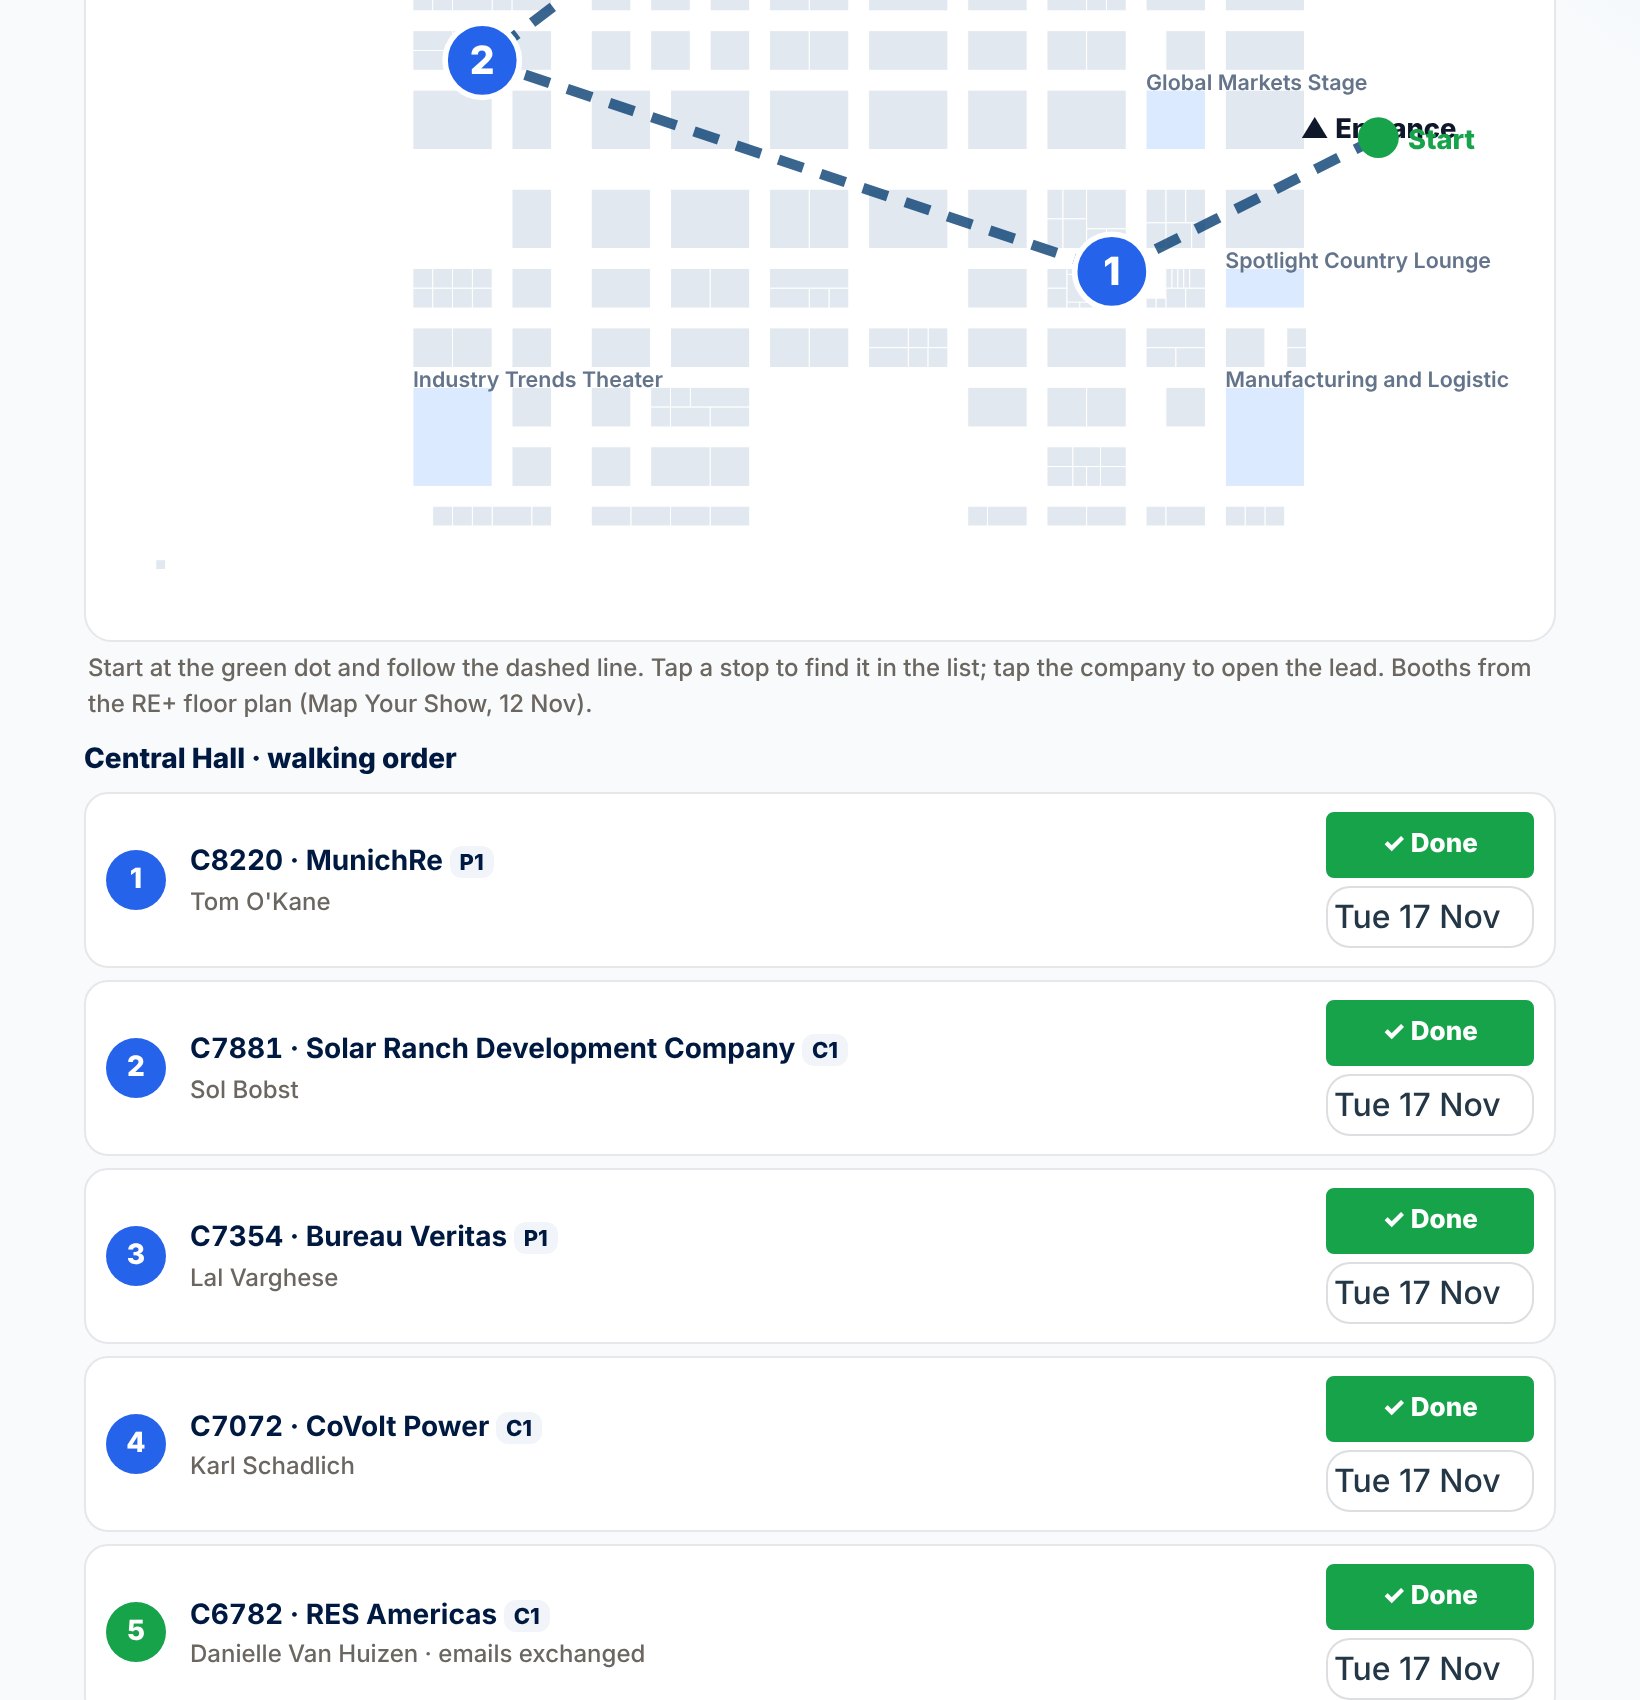
Screens: Vivian’s route for Wed 18 Nov and Tamer’s walking order8
Workshop on our angle of approach
Under Tamer’s leadership we assessed the angle of approach for each client lead and, separately, for partner opportunities. The next twelve slides are the draft strategy we finalise today.
Inputs
Expert discovery Q&A, a market check to 15 Nov, and the lead data above.
Output
Positioning, client and partner approach, and the conditions for large commitments.
Status
Draft, with ten open items listed at the end.
9
The whole picture on one page
Market
US module assembly is plentiful (65+ GW); clean US cells are scarce (about 3 GW early 2026). From 4 December imports land behind Section 232 price floors, and the FEOC test tightens every year.
Where Awendio stands
A credible phased 2 GW plan and non-FEOC supply available now. No operating factory, certification, bankability or warranty backstop yet.
Client angle
Developers with safe-harbored pipelines to 2030. Ask for the second-source share, 100 to 500 MW: a pilot order now and a milestone-gated reservation on small, secured deposits.
Partner angle
Owner’s engineers, advisors, financiers, insurers and bundled-product sellers. They bring the large buyers and close our credibility gaps.
What must happen first
A FEOC legal opinion, dated factory milestones and a named warranty insurer. These three turn the plan into a case a lender accepts.
10
Module lines are plentiful; clean cells are not
65+ GW
US module assembly
Above annual US installs of about 43 GW.
~3 GW
US cells, early 2026
About 22 GW under construction.
38¢ / 22¢
Section 232 floors
Per watt, modules and cells, plus 15%, from 4 Dec.
249%
New trade duties
India; Indonesia 94%, Laos 65% (Sep 2026).
Assessment
Buyers are not short of module suppliers. They are short of cell supply that is FEOC-clean, traceable and priced without trade surprises.
Our approach
Lead with supply structure and cell origin, not module specifications: certified supply now, our own US cells as the long-term answer.
Sources: SEIA via GCN; Canary Media; White & Case; GCN (Sep 2026)11
The tax-credit deadline decides who can use 2027 and 2028 supply
| Project situation | Credit deadline (45Y / 48E) | Fit for Awendio |
|---|---|---|
| Started construction in 2025 | In service by end of 2029 | Strong: 2027 and 2028 deliveries |
| Started 1 Jan to 4 Jul 2026 | In service by end of 2030; FEOC cost test applies | Best: needs FEOC-clean, domestic supply |
| Not started by 4 Jul 2026 | In service by 31 Dec 2027 | 2027 deliveries only |
| Not relying on the credit | None | Buys on price, security, traceability |
Assessment
Our 2028 and later volume fits only safe-harbored projects and buyers who do not need the credit.
Our approach
Qualify on safe-harbored MW and in-service dates first: 2027 needs go to Layer 1, 2028 to 2030 needs to Layer 2.
Sources: OBBBA (Jul 2025); IRS Notice 2025-42; The Tax Adviser (Feb 2026)12
What buyers need, and how far we can answer today
| Buyer need | Market evidence | Our answer | Today |
|---|---|---|---|
| FEOC certainty | Cost test 40% in 2026, rising to 60% by 2030 | Certified non-FEOC supply; legal opinion to come | Partly |
| Price stability | Imports $0.27 to $0.38/W since August; +15% after 4 Dec | Supply priced inside the tariff walls | Partly |
| Domestic content | US-cell modules ~$0.48/W, some sold out; threshold 50% to 55% | Our own US cells from late 2028 | Later |
| Traceability | New trade cases every year | Documented origin per order | Partly |
| Counterparty | 30-year warranty from a new name | Insurer backstop, milestone terms | Open |
Assessment
We answer FEOC, price and traceability partly today, domestic content only from late 2028, and counterparty risk only through contract terms and partners.
Sources: Notice 2026-15; Anza via PV Tech (Sep 2026); Anza (Jul 2026)13
Our angle: one supply structure in three layers
A commercially flexible path to FEOC-clean, increasingly American solar supply: today through strategic sourcing, from 2027 through US module assembly, from late 2028 through our own US cells.
Layer 1 · now
Supply today
Non-FEOC TOPCon modules through sourcing partners; deliveries from September 2026.
For: 2027 in-service projects and pilot orders.
Layer 2 · 2027
Secure future supply
US-assembled modules from our phased 2 GW platform, reserved by MW a year, activated by milestones.
For: safe-harbored pipelines, 2028 to 2030.
Layer 3 · late 2028
Domestic supply chain
Our own 2 GW of US cells with US wafers: the strongest domestic-content position.
For: strategic, multi-year buyers.
Sources: Awendio press release, 22 Sep 2026 (modules 2027); internal plan (cells late 2028)14
A credible plan; the proof is still open
| Element | Status | Detail |
|---|---|---|
| Phased 2 GW US cell and module platform | Public | 22 Sep 2026; RCT Solutions, AtkinsRéalis |
| Non-FEOC modules available now | Public | Via sourcing partners; certificate per order |
| TOPCon glass-glass, 610 to 725 W, up to 23.5% | Internal | Datasheets to publish |
| US cells from late 2028, US wafers | Internal | Wafer deal not yet in writing |
| Factory site, permits, financing | To confirm | No site public |
| UL / IEC / CEC, testing, IE report, insurer | To confirm | None published |
| No Chinese equity, debt, IP, licensing, offtake | To confirm | Legal opinion needed, incl. offshore OEMs |
Assessment
Today our case rests on Layer 1 supply, the plan and our terms. The website’s “100% North American” line must match today’s sourced supply before buyers compare them.
Sources: awendiosolaris.com; press release 22 Sep 2026; internal reference (13 Oct 2026)15
We win as the clean second source, not on scale
| Supplier | US position (2026) | Our opening |
|---|---|---|
| First Solar | Up to 14 GW thin film, US-owned | Crystalline second source |
| Qcells (Hanwha) | Full chain in Georgia; cells since June 2026 | Allocation, flexibility, terms |
| T1 Energy | Ex-Trina modules; Texas cell fab ramping | Ownership history, diversification |
| Canadian Solar | Texas modules; Indiana HJT cells | FEOC restructuring incomplete |
| Illuminate USA | Invenergy and LONGi venture, Ohio | Chinese partner still in place |
| New entrants | Waaree, Suniva, ES Foundry, others | Same newcomer risk; better structure |
Our approach
Ask a 1 GW-a-year buyer for the second or third share, 100 to 500 MW, on terms that carry our risk. Ownership and cell origin make the comparison for us.
Sources: Canary Media (Jan, Jun 2026); PV Tech (Jul 2026)16
Five conditions for a 250 to 500 MW commitment
| Condition | What it takes | Today |
|---|---|---|
| A cleaner structure | Legal opinion: no Chinese equity, debt, IP, licensing or offtake | Open |
| A checkable roadmap | Dated, independently verified factory milestones | Open |
| Terms that carry our risk | Approved deposits, exits, damages and warranty backstop | Drafted |
| A real economic benefit | FEOC certainty, domestic-content path, supply inside tariff walls | Strong |
| A lasting relationship | Bridge supply now, reserved volume next, US cells later | Strong |
Our approach
Lead with conditions 4 and 5 now and share 1 to 3 under NDA as they close. Volume commitments follow when all five hold.
Built from the expert discovery Q&A17
Clients: large, safe-harbored buyers short of clean cells
Tier 1 · 94 leads
Developers and IPPs
250 to 500 MW a year, safe-harbored pipeline to 2030, domestic-content or FEOC strategy.
Meetings: Brookfield, EDF, Boralex, Nexamp, UKA, Treaty Oak, Kruger, Aspen Power.
Tier 2 · 77 leads
EPCs who buy modules
Value delivery certainty, delivered-duty-paid supply and damages.
Meetings: Pure Power Engineering, Willmeng.
Tier 3 · 22 leads
Owners, utilities, co-ops
Value a traceable US chain and a long-lived counterparty.
Meetings: Kendall Sustainable Infrastructure, La Plata Electric.
Our approach
Concentrate on the 96 C1 leads and 13 confirmed meetings. Reach small buyers through distributors and bundled-product partners, not directly.
Source: Solaris console, RE+ 2026 lead data, 15 Nov 2026 (266 client leads at C1 to C4)18
Four ways to commit without betting the project
Start small
Pilot order
Layer 1 volume proves quality, logistics and paperwork first.
Reserve
Capacity reservation
MW a year for 2027 to 2030, a price mechanism and delivery damages.
Gate
Milestone activation
Volume switches on as milestones are verified; free exit if one slips.
Protect cash
Secured deposits
A small LC-backed deposit; most payment after delivery.
Recommended offer
A pilot order now plus a milestone-gated reservation for 2028 to 2030 on small, secured deposits. Terms need finance and management approval before they are offered.
Built from the expert discovery Q&A19
Partners: they reach the large buyers and close our gaps
| Partner type | What they get | What Awendio gets |
|---|---|---|
| Warranty insurers | A new US maker to insure from the start | A warranty backstop that survives insolvency |
| Owner’s engineers | Factory access, audits, QA data | A credible voice in module selection |
| Technical advisors | Input for clients’ FEOC plans | Introductions into developer pipelines |
| Financing partners | FEOC-clean, domestic-content projects | LC facilities, supply-chain finance |
| Bundled products | US modules to package with storage | A channel to smaller buyers |
Our approach
Start with warranty insurers and owner’s engineers: they close the bankability gap that blocks every large client. Offer allocation, early insight and paid mandates rather than referral fees.
Partner types from Awendio’s brief of 13 Nov 202620
Ten things to prove before we lead with them
| Evidence to close | Why buyers need it | Owner · date |
|---|---|---|
| FEOC legal opinion, incl. offshore OEMs | Their tax credit depends on it | Vivian · [date] |
| Site, permits, financing close | Proof the factory will exist | Vivian · [date] |
| Dated milestones: modules 2027, cells 2028 | Basis for milestone-gated deals | Vivian · [date] |
| US wafer agreement confirmed in writing | Domestic content and FEOC depth | Vivian · [date] |
| UL 61730, IEC 61215, CEC listing plan | Module can be used on the project | Vivian · [date] |
| Reliability testing and IE report | Lenders accept the module | Vivian · [date] |
| Warranty insurer named | 30-year promise survives us | Vivian · [date] |
| Layer 1 partners: origin, certificates | Supply we can sell today | Vivian · [date] |
| Terms approved: ladder, LC, damages, DDP | Reps can make an offer | Vivian · [date] |
| Internal price guidance for reps | Answer “what’s your price?” | Vivian · [date] |
Owner: Vivian for all items (15 Nov); dates to set21
Action points for today
1
Follow-up workshop
Walk through every lead and priority deal one by one, set the angle of approach and the responsible person.
2
Owners for the event
Set in the CRM who manages each contact at the show, so daily plans are ready to run.
3
CRM walk-through
How to use it during the show and how to track meeting notes and business cards in it.
4
Finalise our approach
Align internally on the partner and client approach, close the open points in this deck, and produce a reference playbook for client and partner communication.
15 November 2026